 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.

Wild hopes for US rate cuts got shattered, exactly as we predicted. But given the different incentives that the Fed and ECB now face, the relative pricing between the Fed and the ECB could widen further in the coming months. We discuss the implications for rates, the dollar, and the relative positioning in US versus European equities.
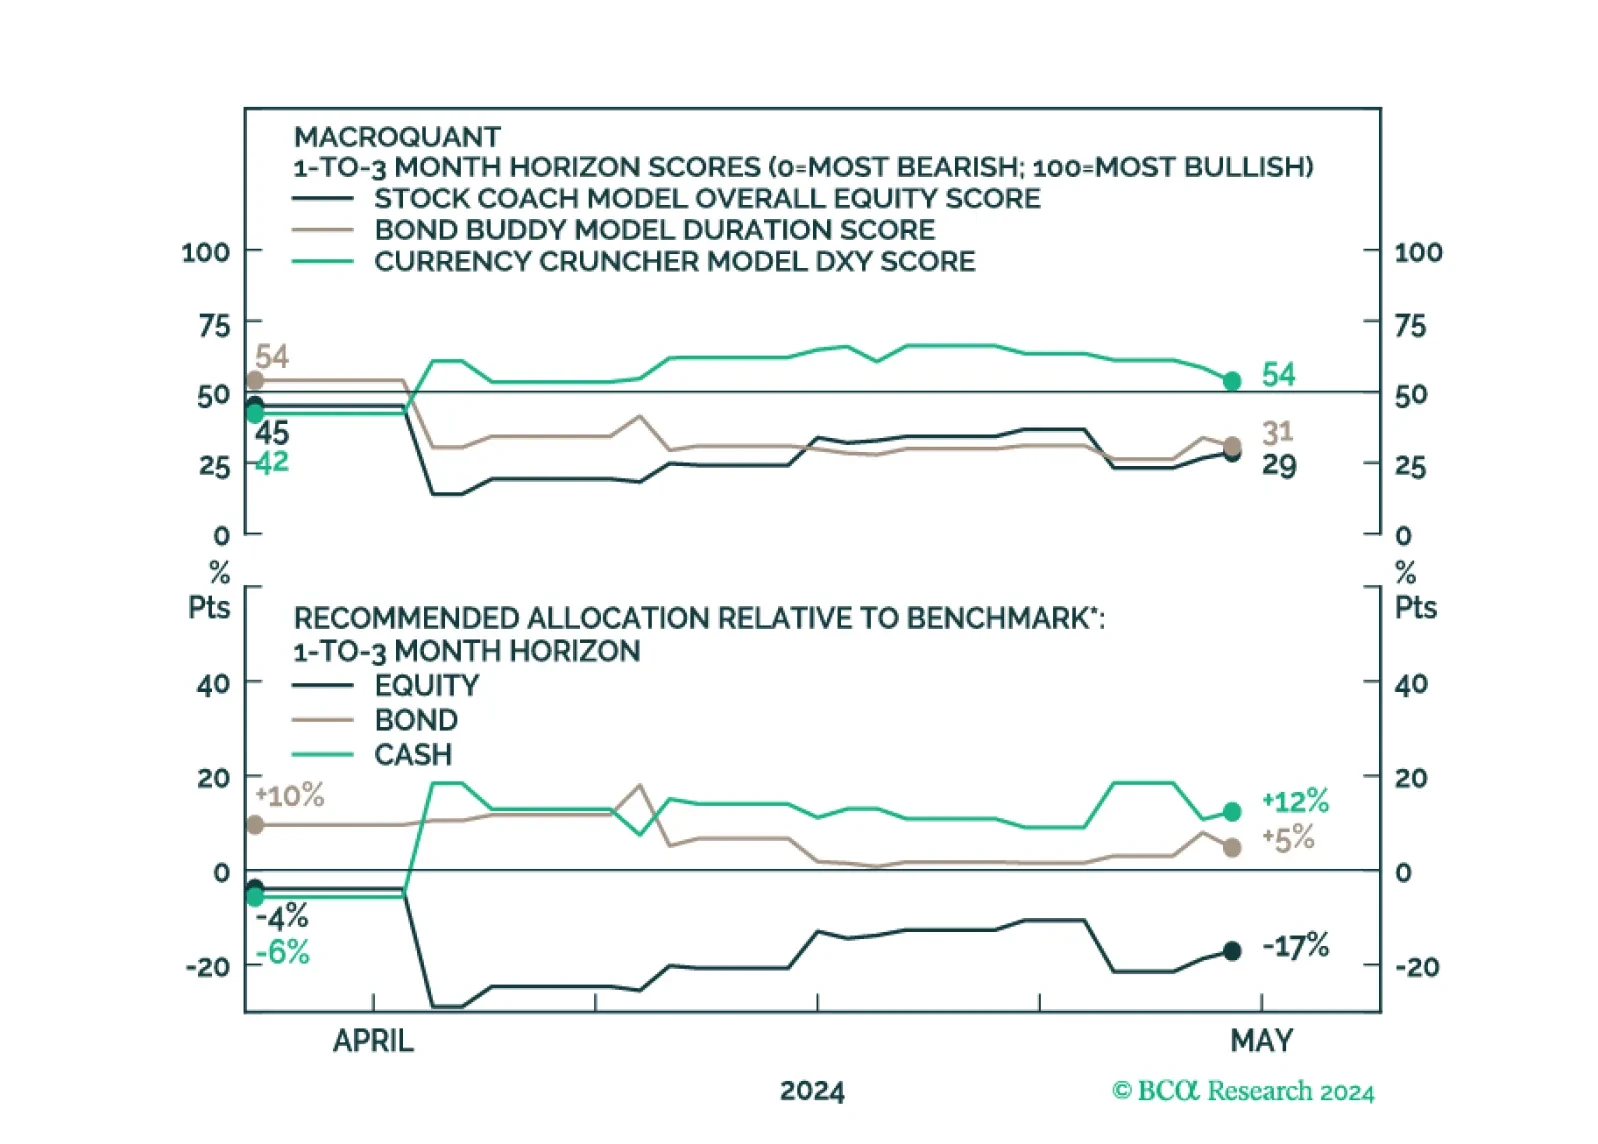
MacroQuant downgraded equities from neutral to underweight on a 1-to-3 month horizon. The model suggests increasing exposure to cash.

We are publishing the chart pack I used during my meetings with clients and prospects in Europe last week. It contains charts on China, global macro, and EM asset classes, all of which are mostly self-explanatory and convey my views and analysis.
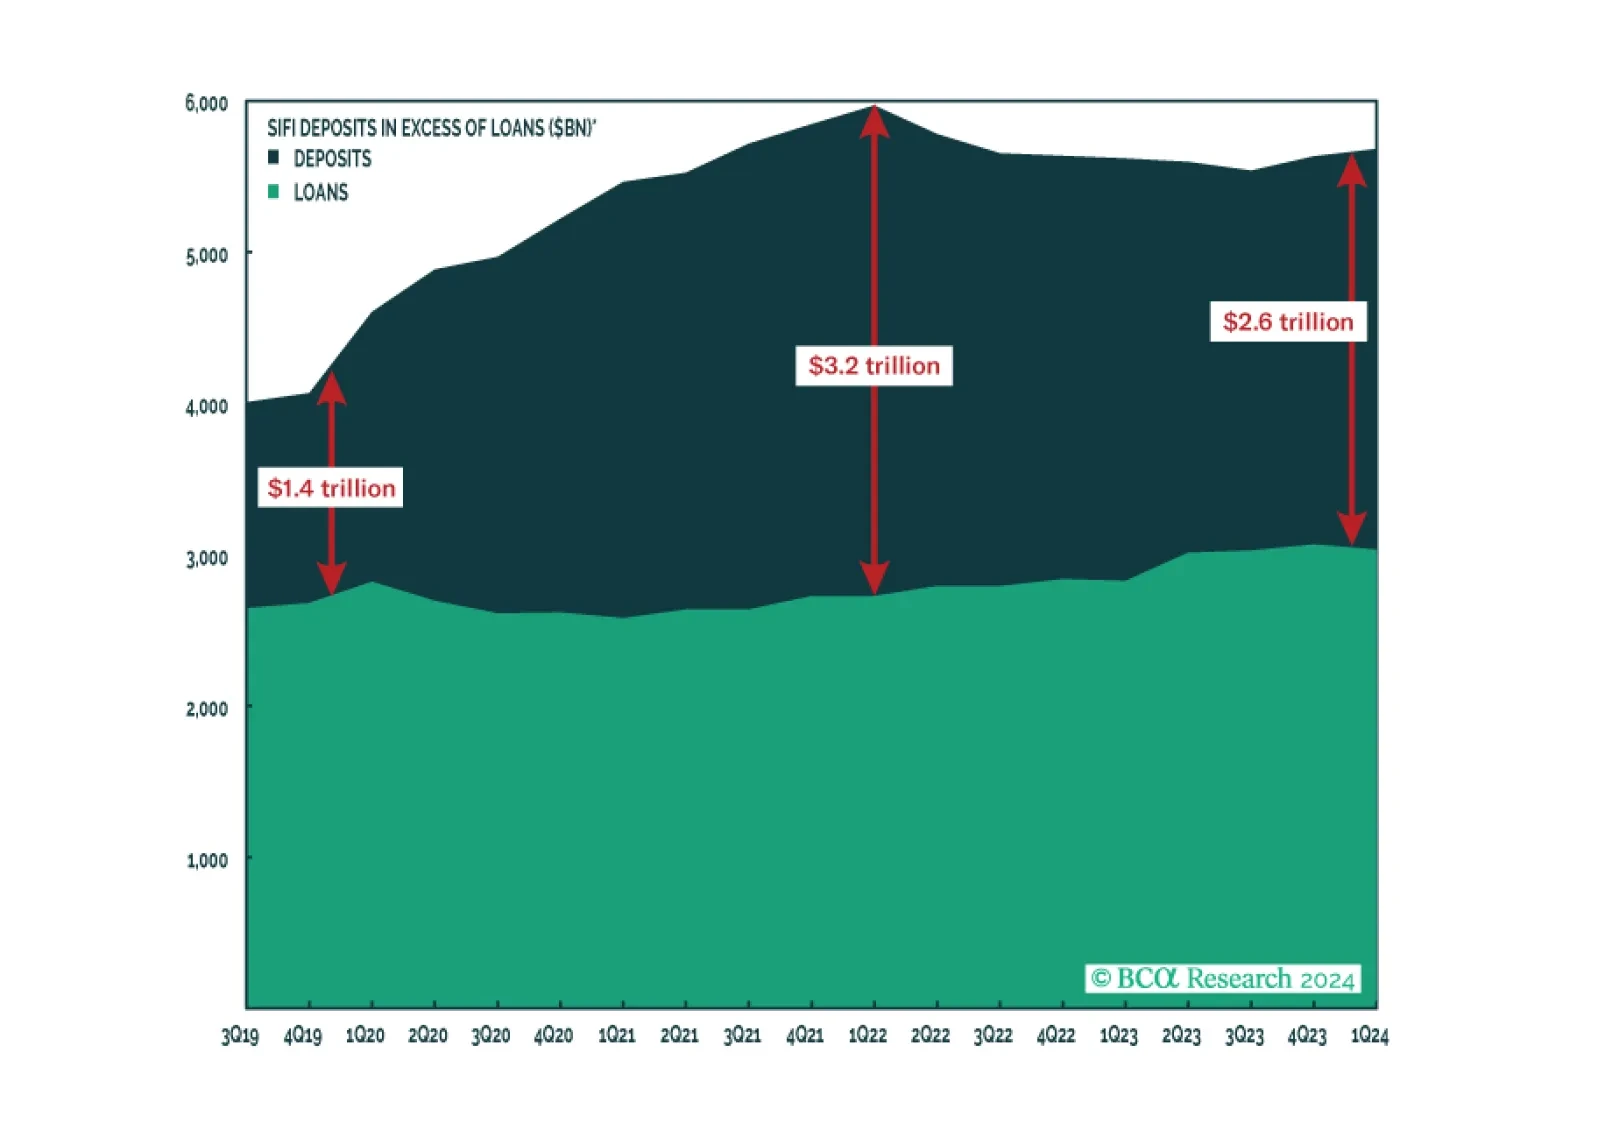
The latest edition of our Big Bank Beige Book suggests the expansion remains intact, though weakness in C’s private-label credit card portfolio could be a harbinger of distress among lower-income consumers. We remain tactically neutral with a bias to turn defensive once clearer signs of a recession emerge.


Investors anticipate a record growth gap between the US and the Eurozone in 2024. Does this skewed expectation create market opportunities?


The disinflation process is over in Poland and Hungary. Only the Czech Republic will see its core inflation meet its central bank target this year. The reason is much tighter labor market dynamics in the first two. Investors should continue to short a basket of CE3 currencies vis-à-vis the US dollar.
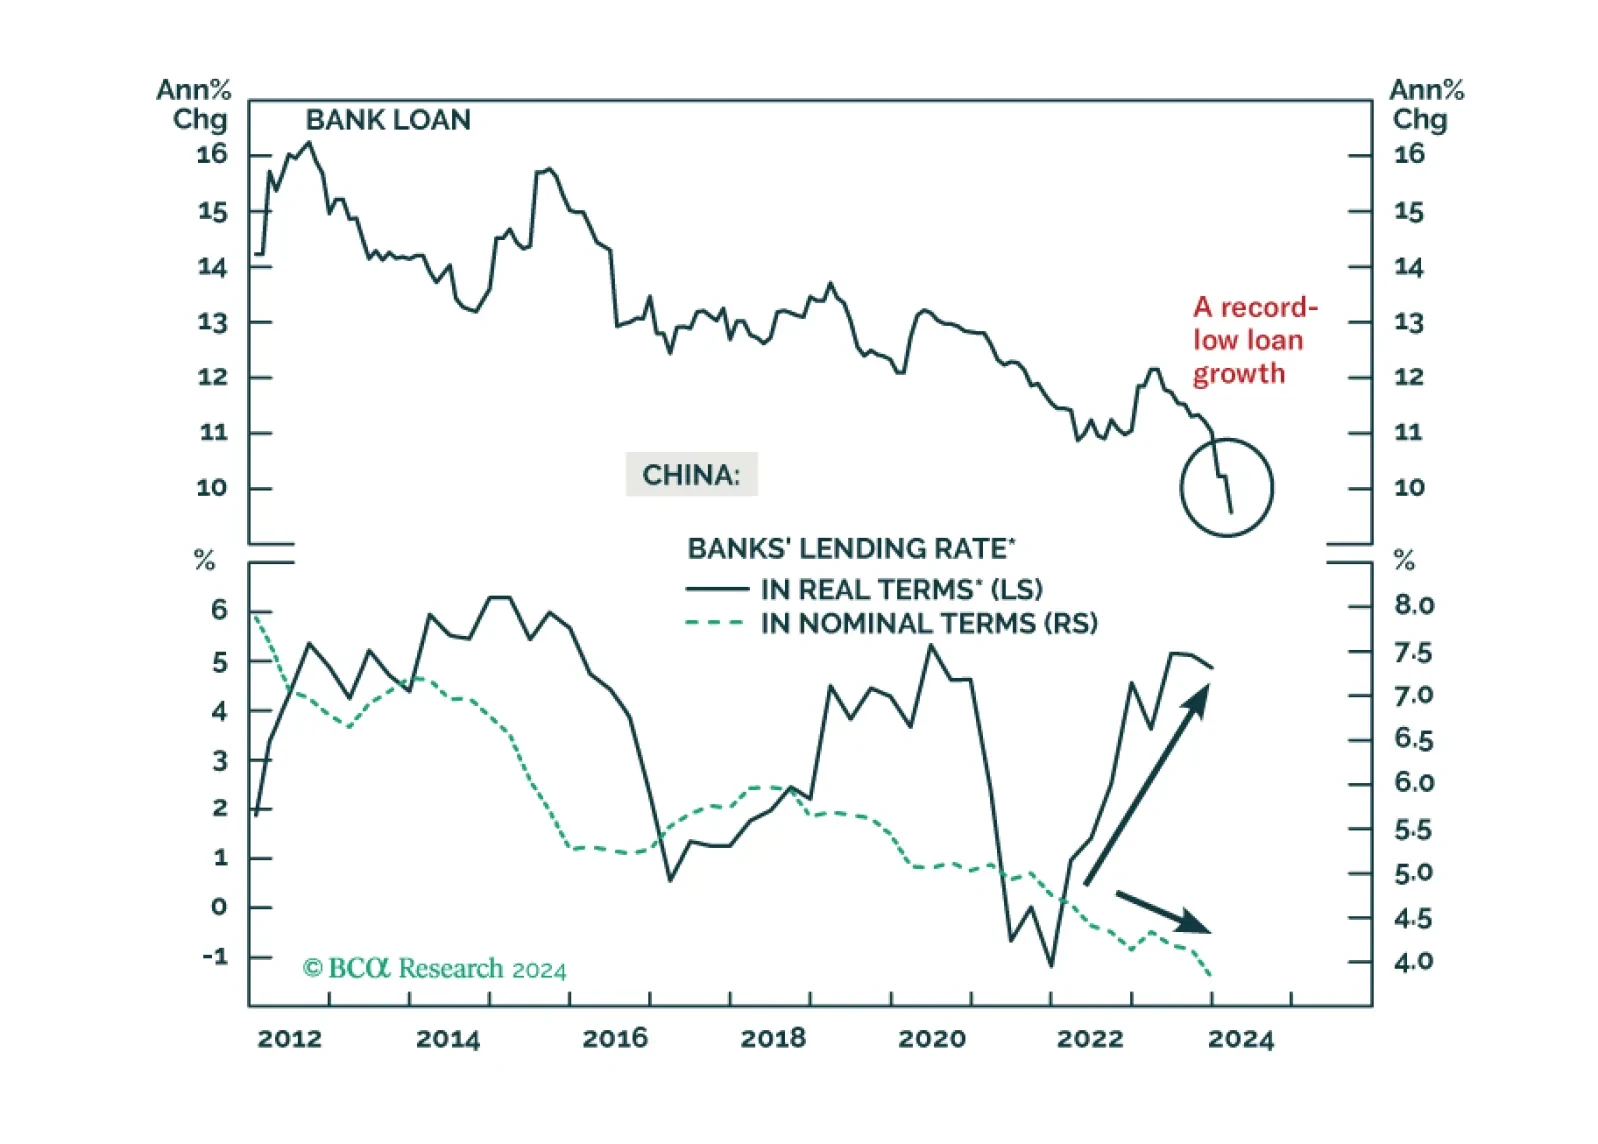
China’s economy is cruising at a very low altitude. The odds are that China’s equity rebound is running out of time. The RMB will continue to depreciate versus the US dollar in the coming months, albeit the pace may be modest.

European profits margins are elevated. Will a mild recession be enough to bring them down?